Every Monday my budget reports to me. It took one prompt and a scheduled task
I used to associate budgeting with deprivation. I thought that if I earned enough, it would sort itself out somehow. That's the trap of having a surplus. You assume extra income lands somewhere useful by default. It doesn't. It leaks, quietly, into nothing you can point at.
A classic budget in an app or a spreadsheet is a gym membership. It works exactly as long as you show up, until you skip a week. To reach the goal, you hire a coach. They motivate you to improve and keep you from quitting. So I made Claude the coach.
The goal is the key, as I said in my previous post. The first thing you need to do is understand WHY you need a budget. My goal is financial independence at 55. I calculated my annual contributions to achieve it and built a budget around them.
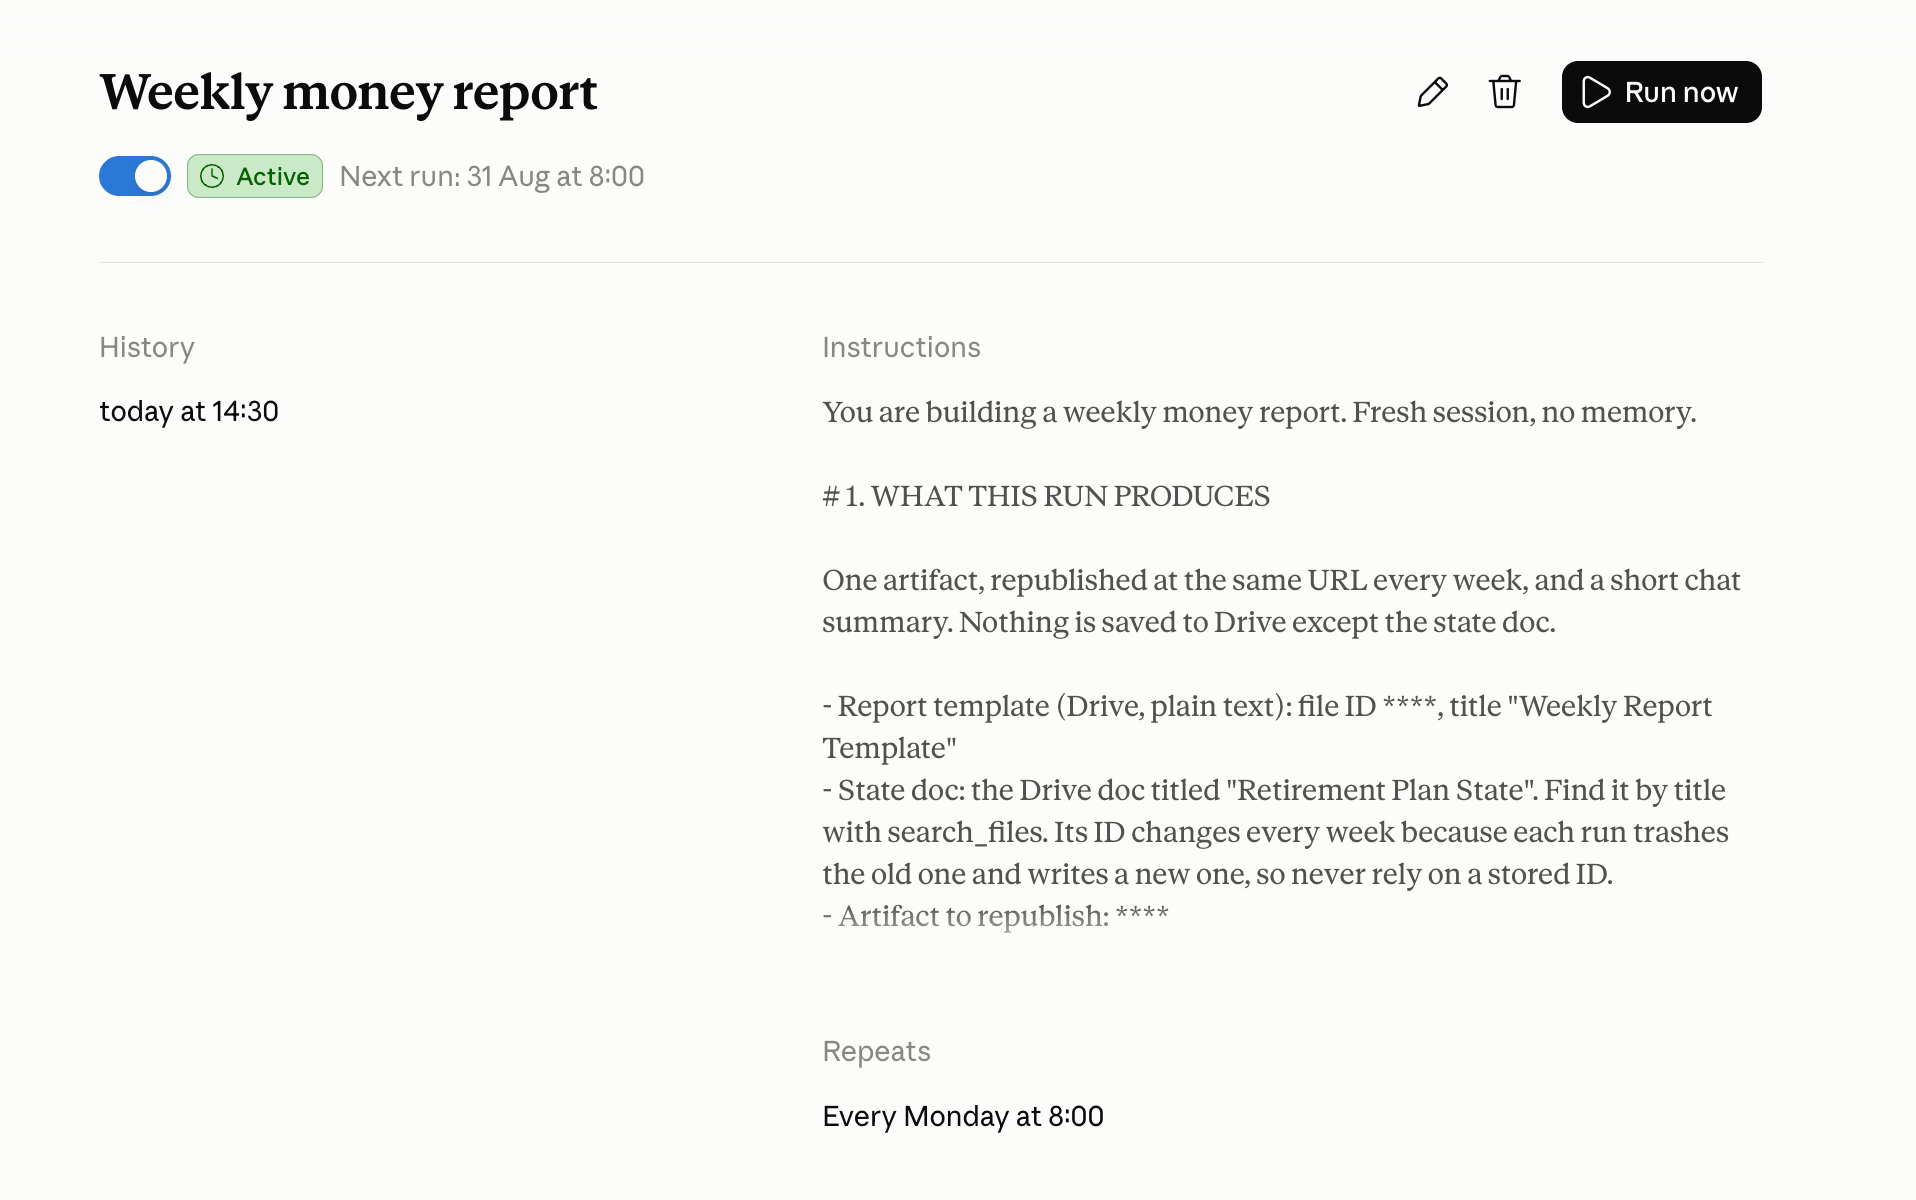
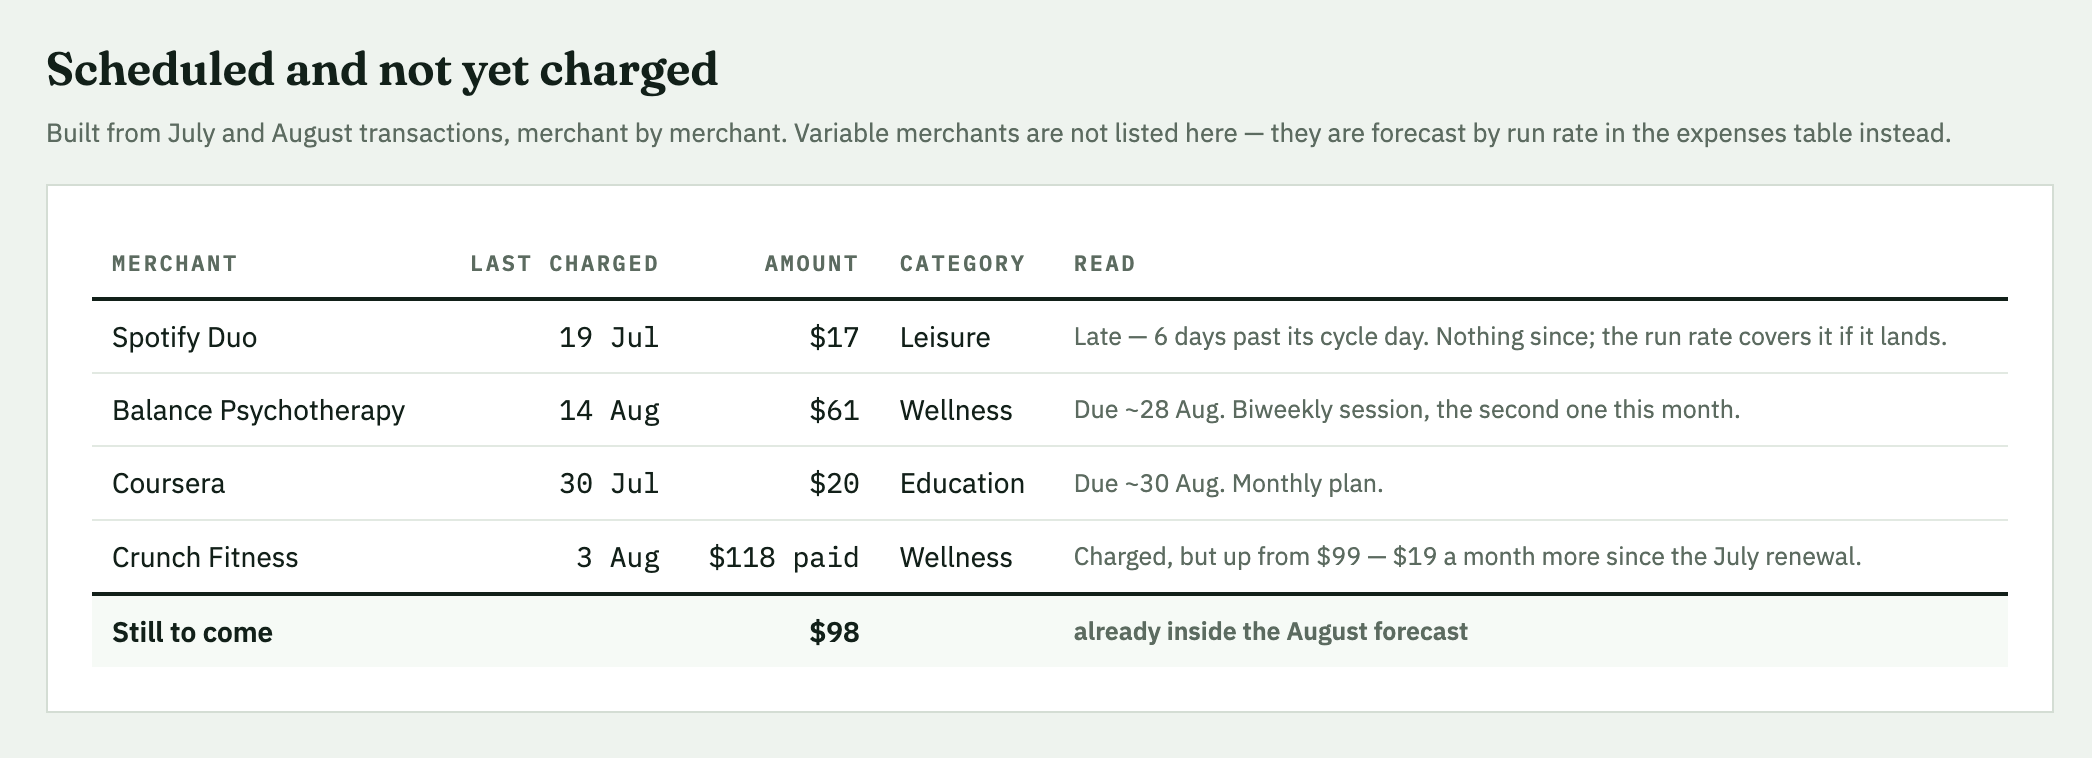
Finances manage themselves. Every Monday at 08:00 a scheduled Claude task connects to finerd over MCP. It reads live data: transactions, budgets, reports, and the recurring payments finerd has already detected. It forecasts the month, republishes one report page at a fixed URL, and sends me a summary under 120 words. For example, this week it flagged my gym quietly raising the membership by $19 a month. I missed the email about this (if there even was one, lol).
And Claude writes back. It updates next month's budget, applies the decisions I approved, refreshes the annual pot balances, keeps the plan and the forecast in sync. I don't open the app to do this anymore. Budgeting happens to me.
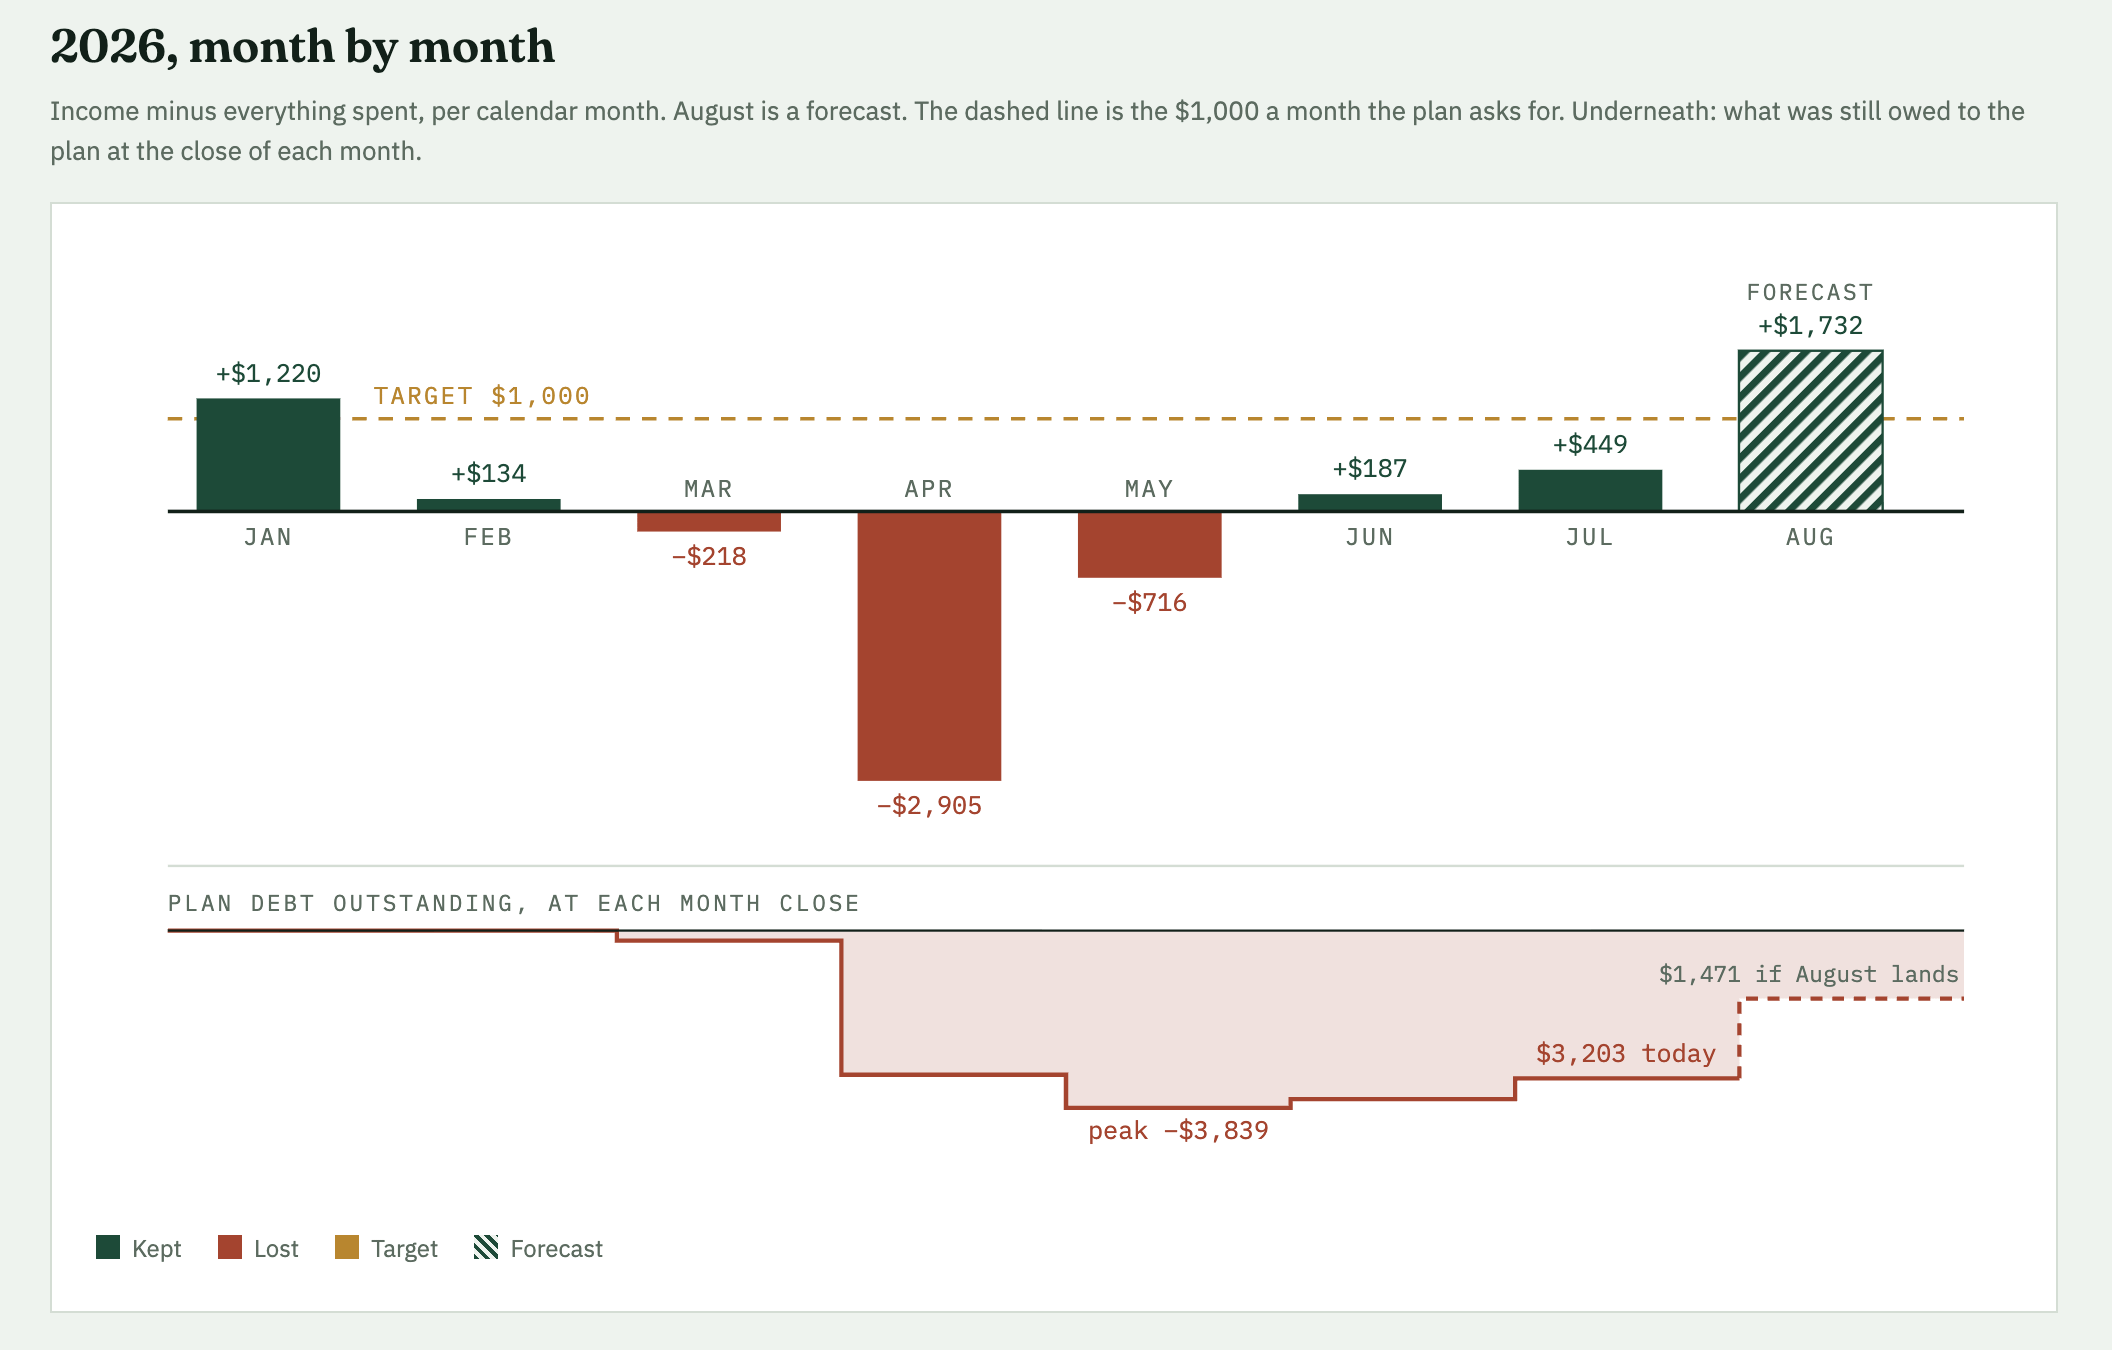
You owe yourself. A budget doesn't control your life. An unexpected show from your favourite band will change the plans. Every splurge is a loan from yourself, and you can afford to forget one. The problem is that decisions like this become a system. Mine dug a $3,839 hole. So it's useful to see what you owe to your goal.
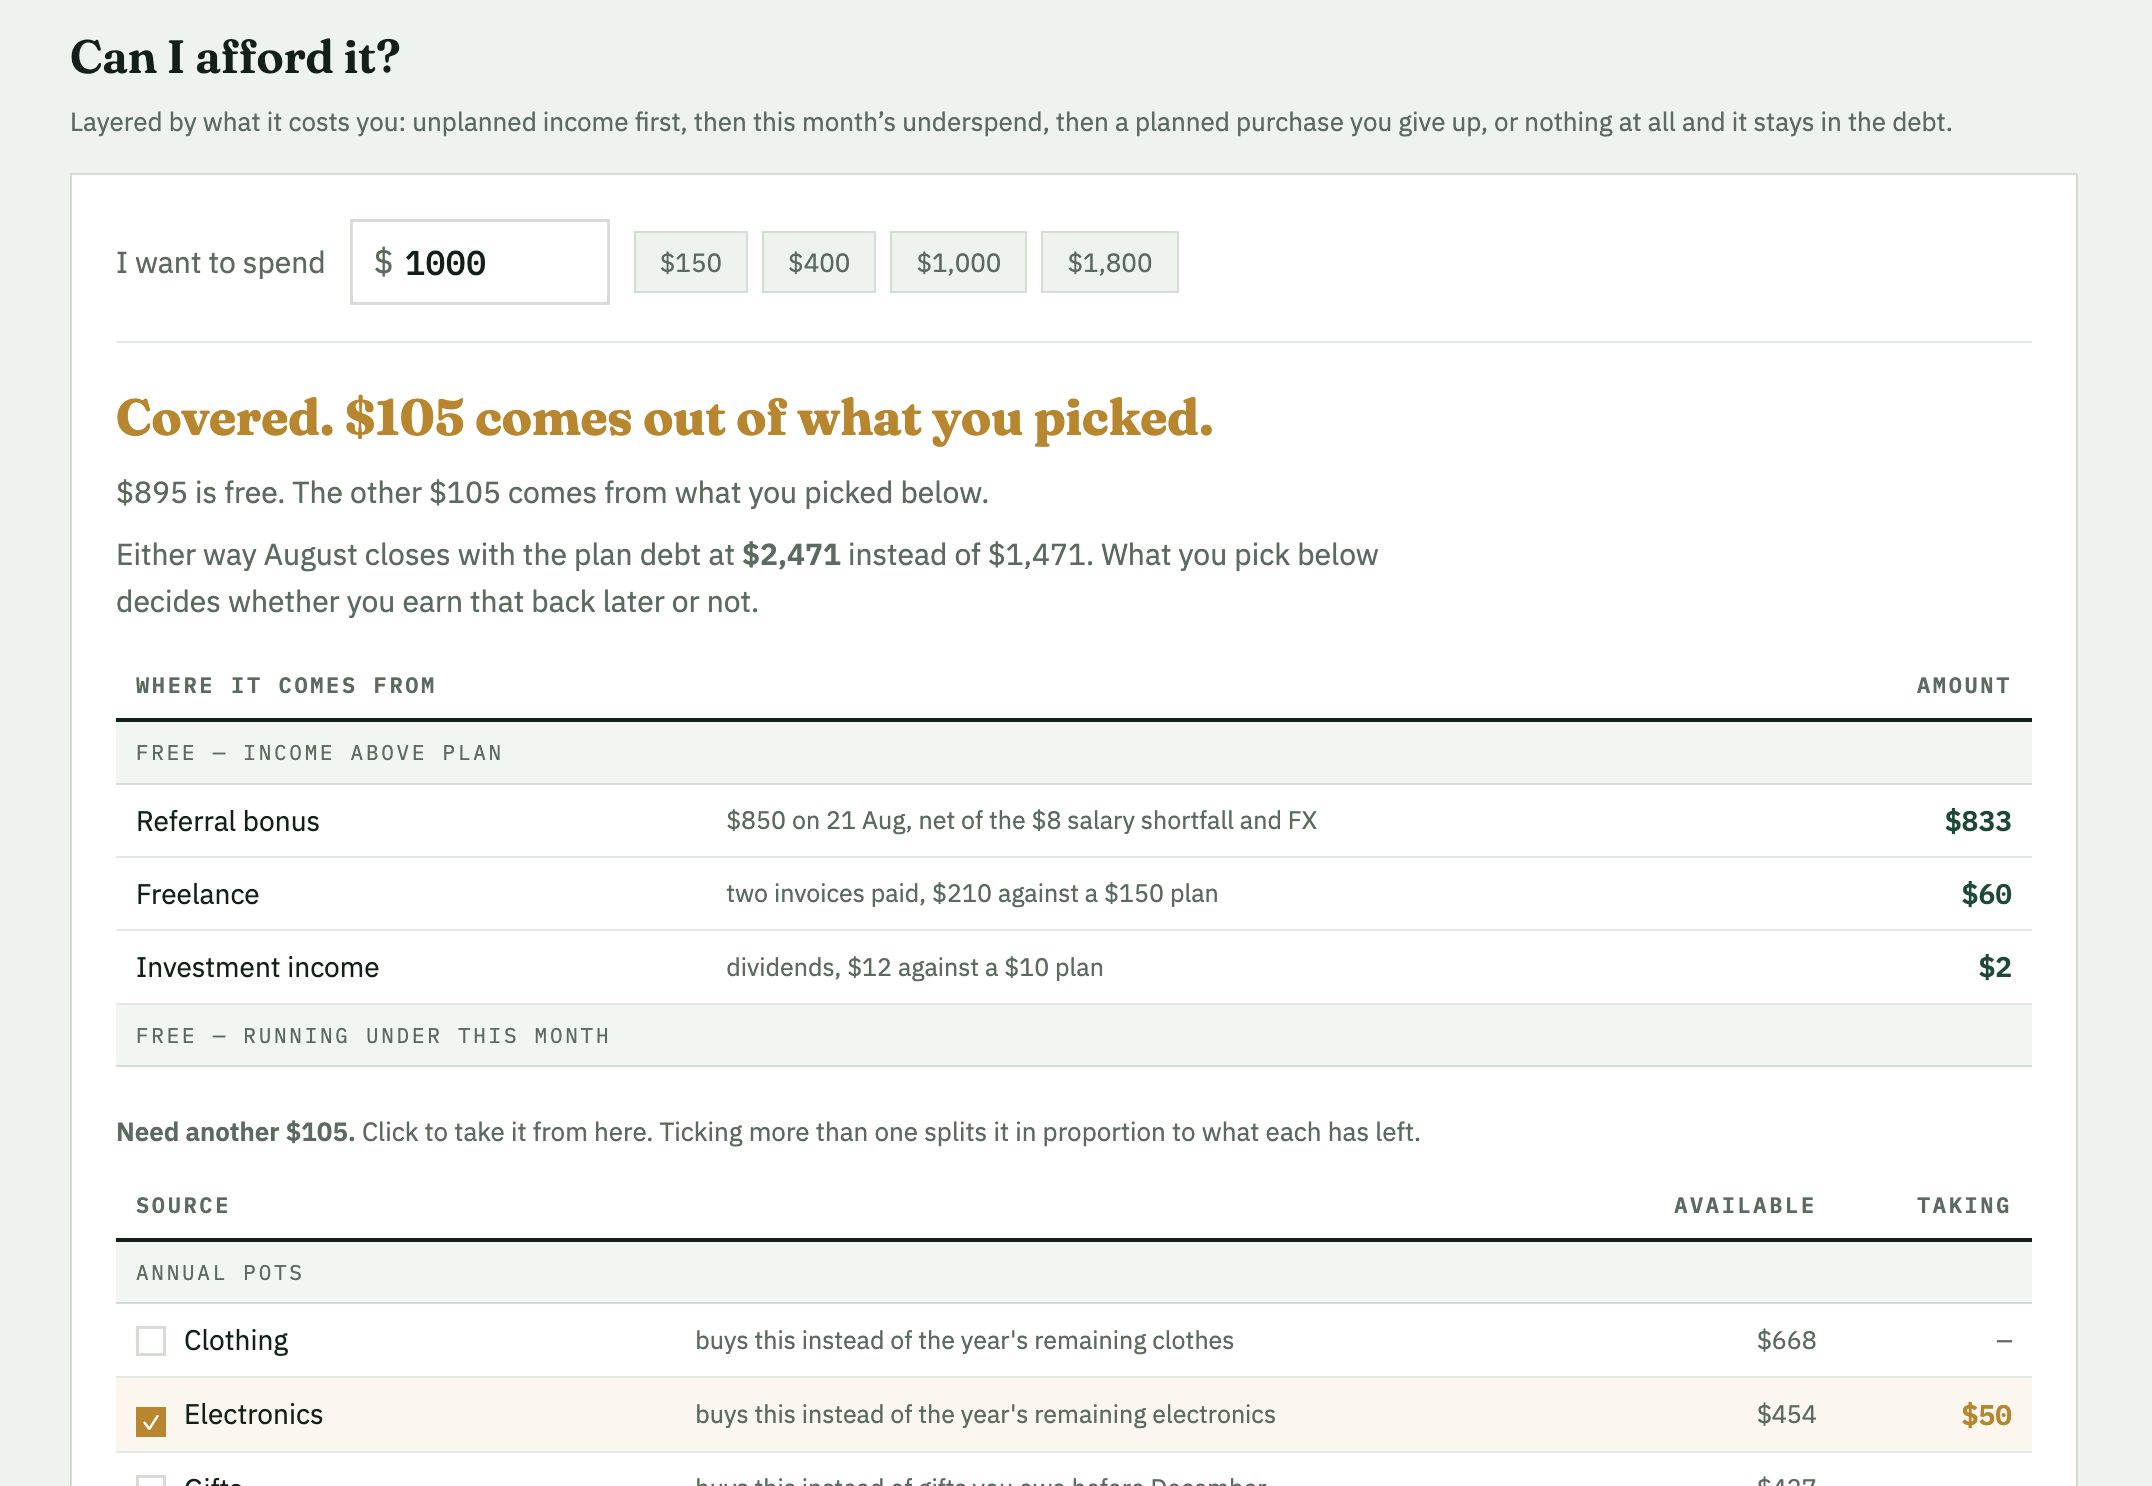
Can I afford it? I built a tool for managing this debt to myself. When I want to spend on something unplanned, I pick the source that funds it. For example, trim dining for the rest of the month or plan a less expensive summer trip. Claude takes my choice and updates next month's budget on its own. The point is to answer one question. Can I afford this without hurting the goal? The useful answer is not "you've exceeded the category." It's "you can cover this if you spend less on X."
The prompt and the template. I'm sharing them, so it's easy to rebuild. Just upload them to a Claude Cowork chat. It asks for everything it needs and creates the scheduled task itself. Yeah, it's huge, but believe me, it contains fixes for every issue I ran into.
Comments